This is a very new website which is building resources for you. It is FREE to you
Better yet you should request my FREE NEWS LETTER because it will give you updates and save you time and money.
Send your request for a free saving newsletter to profwa@gmail.com
We are now in process of adding saving things to this website and the newsletter.


Above is the greatest solution to solving the world's social problems.
Here are 1000 important items including many Secrets that were not NEWS because they were hidden but are items you need to know, many will affect or threaten you and your family. Seriously.
You should get this free little 39 page book because it has life saving info for you.

World`s Most Needed Song the Kindness Song 3 versions Kindness Song
Best Tip on saving is to Shop around, ask others, network, look at as many sources as possible including this page and our FREE Newsletter.
If you are low income and in need of food you may qualify for food assistance from State of Michigan and also get food from one of several area food pantries. Visit the State of Michigan, Gleaners or Forgotten Harvest websites. Here are links.
michigan.gov
Gleaners
Gleaners food drive in 4401 8 Mile Rd, Warren, MI 48091
Forgotten Harvest
All Tuesdays and Fridays


BEST BARGAIN IN WARREN. And they are fast and even have an under floor well so no need to put car on hoist. 4695 E. 9 Mile Rd. Warren Mi 48091 586 486 5727 Mon-Sat 8 AM-6 PM

Oldtime variety store with many bargains. Nearby is Dollar Tree with many more bargains. Behind them around the block in front of Dave's Market is Dollar Village which has great prices on tools and many other items not found elsewhere.

Dollar Village has real bargains on many items.
The king of resale if Byron's Resale at 24805 Van Dyke a block South of 10 Mi his store is full of great bargains.

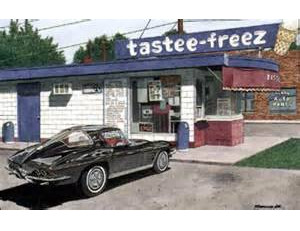
Across the street is Tastee-freez the favorite spot in Center Line and Middle Warren since the 1960s.
Near by is our great guy who fixes TVs


May 10 2026 The Amazing super Warren attraction The Kutchey Family Market Opened.
They have Great deals on Flowers to plant and on hanging pots.
Kutchey Family Market 27825 Ryan Rd. Warren, MI 48092 586.806.2262
HOURS MON-FRI | 9-7 SAT-SUN | 9-5
Our best bargain Coney restaurant

Next to the Coney is our very long time excellent car repair specialist Mo. He has done excellent work for me and many others.

Learning Gizmos for teacher and student school supplies 23601 Van Dyke, Warren, MI 48089 Your go-to for Games, Toys, Books, and more! http://www.learninggizmos.com/

Best place for meetings, beauty and relation while enjoying great sandwiches and more and helping our schools is Gathering Grounds. Baking done by the Rising Star Academy.
Our Center Line Salvation Army Store has great bargains. On Van Dyke just North of 10 Mile.
Our oldest and busiest and most popular restaurant which was the Howard Johnsons back in 1950s is now Haneys run by Rising Star Academy.


We found a treasure place in Warren. Several people told us about this. When I finally visited I found something I had been searching for, for years. Carl must be the King of antiques as he has thousands of items. Antique Gallery 11564 13 Mile just West of Hoover in Warren.
Woodside Bible Church on 27400 Hoover just North of 11 Mile has a thrift shop and food pantry open Mondays 12-3 and Fridays 9am-12 check with 586 758 4750. website https://woodsidebible.org/locations/warren/
Shelter and Housing help.
Because of continuing failed leadership there is a shortage of affordable housing and emergency shelters. Call 211 for locations. The two main locations in Warren are at the Salvation Army compound on Mound between 8 and 9 Mile roads and Friend of Father on 9 Mile at Memphis West of Van Dyke and Turning point is establishing a new shelter. The Michigan Department of Health and Human Services office is at 13041 E.10 Mile Warren just West of Schoenherr and has resources.
Also Call your Local Michigan Works! One-Stop Service Center at 800-285-WORKS (9675)
Local churches have been known to help in emergencies but please only contact big churches and as a last resort.
Saving money involves combining classic strategies like meal planning with advanced digital tools such as AI price trackers.
Smart Grocery & Household Savings
Set a `Buy Price`: Identify your 15 most frequently purchased items (e.g., coffee, milk) and determine a target `good deal` price for each. Only stock up when the price is at or below this target.
Weaponize Unit Prices: Ignore `sale` signs and focus on the price per ounce or count, often found in small print on digital shelf tags. Large `family size` packs are sometimes more expensive per unit than standard sizes.
Shift to Store Brands: Private labels are typically 20%-30% cheaper and often nutritionally equivalent to name brands.
Reduce Food Waste: Households can save nearly $3,000 annually by tracking inventory and using leftovers creatively. Use `lazy batching` to prep versatile base ingredients (like grains and proteins) instead of rigid, unique meals.
Shop `Markdown Windows`: Visit stores during specific times, such as one to two hours before closing, to find manager's specials on meat, bakery, and produce. Strategic Shopping & Retail Habits
Use AI Price Trackers: Use apps like Basketful, Flashfood, or Honey to forecast markdowns and receive alerts when prices drop below your target.
Apply the 30-Day Rule: For non-essential purchases, add items to a wishlist and wait 30 days. If the desire persists after the `cooling-off` period, proceed with the purchase; often, the impulse fades.
Buy Off-Season: Purchase winter gear in January and summer items during fall transitions to secure deep discounts.
Audit Subscriptions: Regularly review recurring charges. Use browser extensions to find promotional rates for streaming services or cancel and wait for `come back` offers. Discounted Gift Cards: Buy gift cards for supermarkets or gas stations at less than face value through sites like CardCash or Raise.
Digital Tools & Rewards
Cashback Portals: Use apps like Rakuten or TopCashback for online shopping to earn a percentage back on every purchase.
Receipt Scanning: Snap photos of your receipts using Fetch, Ibotta, or Upside to earn points or cash rewards on everyday groceries and gas.
Loyalty Stacking: Combine manufacturer coupons with store loyalty programs and cashback apps on a single transaction to maximize total savings.
AI responses may include mistakes. For financial advice, consult a professional.
4 shopping tips for 2026 that`ll save you money (almost anywhere)
Jan 2, 2026 The smart habits that keep you from paying full price * Buy prices, not products. Decide what `good deal` is before you shop.
How to Save Money at the Grocery Store in 2026
Nov 21, 2025 Predict Price Drops Before They Happen. One of the biggest 2026 upgrades is using data, not guesswork. AI-powered apps like Basket...
26 ways to save money in 2026 Yahoo Jan 8, 2026 Food and meal savings * 1. Prepare meals at home: Cooking your own lunches and dinners saves money and reduces food waste. Make extra portions and freeze leftovers for quick, ready-to-eat meals.
2. Plan your week's meals: Map out lunches and dinners in advance to avoid last-minute takeout or grocery runs. This ensures you buy only what you need.
3. Follow sales cycles: Many products are cheaper at predictable times of the year. Stock up on seasonal sales, like canned soups in January or frozen foods in March.
4. Buy store brands: Private-label products often taste just as good as name brands, while costing 20%-30% less.
5. Use coupons strategically: Combine paper, digital and store coupons with sales to maximize savings. Check weekly circulars and apps to plan your shopping list.
6. Reduce food waste: Track what you buy, store it properly and use leftovers creatively. This can save nearly $3,000 per household each year, according to the Environmental Protection Agency.
7. Limit alcohol consumption: Cutting back on drinks can significantly reduce monthly expenses and improve overall health.
Household and DIY
Skip expensive chemical cleaners and use natural alternatives like vinegar, lemon, or baking soda for countertops, stains and deodorizing.
8. Make your own cleaning supplies: Skip expensive chemical cleaners and use natural alternatives like vinegar, lemon, or baking soda for countertops, stains and deodorizing.
More in Lifestyle
The Costco Household Product You Should Steer Clear Of, According To Customers Hunker
Shopper thrilled after stumbling upon cult-classic item for cheap at local thrift store: 'It seems brand new'
9. Declutter and sell items: Turn unwanted clothing, tools, or household items into cash by selling online on Poshmark, ThredUp, Mercari, or Facebook Marketplace.
10. Consign high-quality items: Take clothing, toys or accessories to consignment shops to earn a share of the sale while clearing space at home. Pop-up events like the bi-annual Pass it On! sale is another great way to net some quick cash.
11. Repair instead of replace: Don't just toss out what no longer works. Use local Repair Cafes for broken items instead of buying new ones, saving money and reducing waste.
12. Make sure your home is air tight: Ensuring your home is properly insulated is the simplest way to reduce high energy consumption and soaring costs, yet it is one of the most overlooked ways to improve a home's comfort and efficiency
13. Try gardening:Starting a home garden can save money, provide fresh produce and offer a rewarding sense of accomplishment. Even beginners can enjoy growing their own fruits and vegetables while taking control of their food supply.
14. Upcycle old furniture:Give new life to pieces you already own by refinishing or repainting them to match your current style. Not only can this refresh your home, but it can also be a way to earn extra money by selling updated items.
Financial management
Consider zero-interest balance transfer cards to stop accumulating interest and pay down debt faster. (Keith Srakocic)
15. Automate savings: Set up automatic transfers from your paycheck into a savings account to build your nest egg without thinking about it.
16. Reduce debt strategically: Consider zero-interest balance transfer cards to stop accumulating interest and pay down debt faster. Why pay a 12%, 16% or 24% interest rate, when you could pay zero percent for 12, 18 and sometimes 21 months?
17. Compare insurance rates: Shop around for auto, home or renters insurance. Bundling policies and raising deductibles can lower premiums.
18. Switch banks for perks: Look for accounts offering cash bonuses, higher interest rates, or other incentives while making sure fees don't outweigh benefits.
19. Stash your spare change: Apps like Acorns, Qapital, and Chime round up your card purchases to the nearest dollar, automatically saving or investing the difference. It's an easy, hands-off way to grow your savings without thinking about it.
20. Cancel unused subscriptions: Review streaming, software or gym memberships regularly. Keep only what you actually use.
Smart spending and discounts
Before you blow out the candles on your next birthday cake, make sure you don't blow your chance at a windfall of freebies.
21. Try money challenges: Turn saving into a game with small, achievable goals. Daily or weekly savings habits make progress feel manageable, keep your budget on track, and help turn good intentions into long-term financial results.
22. Take advantage of discounts: Take advantage of birthday deals, senior discounts, college student deals, happy hour specials to save on dining, entertainment and travel.
23. Redeem unused gift cards: Check drawers for forgotten gift cards. Using or selling them prevents wasting money and adds extra value.
24. Shop through cash back portals: Earn rewards on everyday online purchases by using portals or apps that give you a percentage back.
25. Control impulse spending: Instead of buying on a whim, take a screenshot of tempting items and wait before deciding. This pause helps curb spontaneous purchases and save money.
26. Subscribe to the Shopportunist newsletter: Get weekly deal alerts, money-saving tips, and more delivered straight to your inbox every Friday morning.
This everyday expense has jumped 55% here`s how to cut it
Over the past few years, inflation has taken a growing bite out of household budgets across the U.S.
One essential expense that has skyrocketed is car insurance. Nationwide, the average cost of car insurance has surged 55% since 2020, according to the Bureau of Labor Statistics.
Car insurance is a major recurring expense, and many people overpay without realizing it. According to Forbes, the average cost of full-coverage car insurance is $2,149 per year (or $179 per month).
However, rates can vary widely depending on your state, driving history and vehicle type and you could be paying more than necessary.
By using OfficialCarInsurance.com, you can easily compare quotes from multiple insurers, such as Progressive, Allstate and GEICO, to ensure you`re getting the best deal. Shopping around can help drive down your rates, and potentially get you a better deal.
Even better, in just two minutes, you could find rates as low as $29 per month. Keep in mind that you can often cancel your policy before it`s up for renewal, just look out for any early cancellation fees.
And it`s not just your car that might be costing you more than it should. Home insurance costs have also risen and it`s another major expense where smart shoppers can save big.
With OfficialHomeInsurance.com, comparing home insurance rates is fast and hassle-free. Just fill in a bit of information and the platform will instantly sort through over 200 insurers to find you the best deals available in your area.
You`ll be able to review all your offers in one place and quickly find the coverage you need for the lowest possible cost, saving an average of $482 a year.
Read More: Approaching retirement with no savings? Don`t panic, you're not alone. Here are 6 easy ways you can catch up (and fast)
Put your spare cash to work
One of the easiest ways to cut financial waste is by putting your spare cash to work instead of letting it sit idle.
If you`re building a financial safety net, a high-yield account like a Wealthfront Cash Account can be a great place to grow your emergency funds, offering both competitive interest rates and easy access to your cash when you need it.
A Wealthfront Cash Account can provide a base variable APY of 3.30%, but Moneywise readers get an exclusive 0.65% boost over their first three months for a total APY of 3.95% provided by program banks on your uninvested cash. That`s ten times the national deposit savings rate, according to the FDIC`s January report.
With no minimum balances or account fees, as well as 24/7 withdrawals and free domestic wire transfers, you can ensure your funds remain accessible at all times. Plus, Wealthfront Cash Account balances of up to $8 million are insured by the FDIC through program banks.
But even your spare change can be put to work. Micro-investing apps like Acorns let you invest small amounts automatically, turning everyday purchases into long-term investments.
When you make a purchase on your credit or debit card, Acorns automatically rounds up the price to the nearest dollar and invests the difference the coins that would wind up in your pocket if you were paying cash into a diversified portfolio of ETFs.
Buying a coffee for $3.40? The app rounds it up to $4 and invests the extra $0.60. Over time, those small amounts can add up especially if you`re consistently spending and saving.
It`s a simple, set-it-and-forget-it way to build wealth from money you might not even miss and, if you sign up today with a recurring monthly investment, Acorns will add a $20 bonus to help you begin your investment journey.
Don`t let hidden expenses drain your budget
If you want to improve your finances, a key step is understanding where your money actually goes each month.
You could try tracking all your expenses for 30 days and sort them into two categories: essentials like rent, groceries, utilities and healthcare and discretionary spending, such as dining out, entertainment, shopping and hobbies.
This breakdown not only shows you where your money is going, but also highlights the hidden leaks the forgotten subscription, the auto-renew you didn`t notice, or the small impulse purchases that quietly add up.
A quick daily check-in of your accounts can show you exactly where your money is going.
An app like Rocket Money can easily flag recurring subscriptions, upcoming bills and unusual charges by pulling in transactions from all your linked accounts.
This can help you cut unnecessary costs, and then you can manually redirect savings straight into your retirement fund. No spreadsheets, no guesswork, no stress. Small habits like this can make a big difference over time.
Rocket Money`s intuitive app offers a variety of free and premium tools. Free features include subscription tracking, bill reminders and budgeting basics, while premium features like automated savings, net worth tracking, customizable dashboards, and more make it easier to stay on top of your retirement contributions and overall financial goals.
Focus on building
automated systems rather than relying on willpower. By targeting high-impact areas like housing, groceries, and utilities, you can significantly reduce your monthly burn.
Core Financial Management
Automate Savings: Set up automatic transfers from your paycheck to a high-yield savings account. Even small amounts, like $20–$60 per week, build significant momentum over time.
Track Spending: Use AI-powered apps like YNAB, Copilot, or Monarch Money to automatically categorize expenses and identify hidden leaks. Rule of Friction: Delete saved credit card information from shopping apps and unsubscribe from marketing emails to curb impulse spending. Apply the `30-Day Rule`: For non-essential purchases, wait 30 days before buying. Often, the initial impulse fades, saving you from a `silly unforced error`.
Housing & Utilities
Optimize Your Space: If renting, negotiate your lease or consider a roommate to split costs. If buying, keep mortgage payments between 25%-35% of take-home pay to maintain financial flexibility.
Reduce `Vampire Loads`: Use smart power strips to completely shut off electronics (like TVs and game consoles) that draw power even when `off`.
Leverage Off-Peak Rates: Shift high-energy tasks, such as running the dishwasher or laundry, to late-night hours when electricity rates are often lower.
Weatherize Your Home: Sealing air leaks around windows and doors can save 10%-20% on heating and cooling costs.
Food & Groceries
Master Meal Planning: Map out your week's meals to avoid last-minute takeout, which is often a household's third-largest expense. Buy Store Brands: Private-label products are typically 20%-30% cheaper than name brands with similar quality.
Use Salvage Food Apps: Use apps like Too Good To Go or Flashfood to buy surplus groceries and restaurant meals at steep discounts. Strategic Bulk Buying: Stock up on non-perishables (rice, beans, toiletries) when they are on sale rather than buying them at full price when you run out.
Lifestyle & Entertainment
Rotate Subscriptions: Audit your streaming services quarterly. Instead of paying for all of them, subscribe to one for a month, watch what you want, and then switch.
Utilize Public Resources: Your local library offers free books, movies, and sometimes even tools or classes. Thrift for Quality: For clothing and furniture, shop at consignment stores. Thrifting is projected to be a dominant trend in 2026 for both cost savings and sustainability.
Free Leisure: Seek out `no-spend` activities like hiking, community festivals, or free museum days.
For personalized planning, tools like the NerdWallet Budget Calculator or Rocket Money can help you audit and automate these steps. AI responses may include mistakes. For financial advice, consult a professional.
2026 401(k) limits range from $24,500 to $35,750 depending on age-based catch-up eligibility.
One year of maxed contributions becomes $63,547 to $92,726 after 10 years at 10% returns.
A year of maxing out a 401(k) can lead to an account balance that`s close to, or higher than, the median balance among middle-aged Americans.
Investors rethink 'hands off' investing and decide to start making real money
It's a good time to start setting your goals for how much you'll contribute to your retirement accounts this year. For many people, a workplace 401(k) is the best retirement account to contribute to because it's easy to invest money in a workplace plan. You can just sign up to make contributions from each paycheck. In many cases, your employer may also match at least part of your contributions.
In 2026, you can invest a maximum of $24,500 if you are 50 or under. If you are 50 or over, you are eligible for an additional $8,000 catch up contribution, bringing the total amount you are allowed to contribute up to $32,500. And, if you are between the ages of 60 and 63, you can invest an extra $11,250 in catch-up contributions instead of an extra $8,000 -- which means that you can put a total of $35,750 into your account.
So, if you decided to invest the full amount this year, how much would this turn into after a decade? Let's take a look.
How much money would you end up with in a decade after maxing out your 401(k) in 2026?
The table below shows the amount of money that you would end up with if you maxed out your 401(k), depending on whether you are eligible for catch-up contributions or not. Since the S&P 500 has pretty consistently produced 10% average annual returns, this assumes that you earned 10% per year on your investments. It also assumes you did not get any employer matching contribution, and that you didn't make any other investments over the decade that you left your 401(k) funds in the market.
Investment amount Amount you'll have after a decade $24,500 - $63,546.69 - $32,500 $84,296.63 - $35,750 - $92,726.29
This means that maxing out your contributions in a single year and leaving your money alone for a decade could leave you with a retirement account balance almost as large as the $67,796 median 401(k) balance among Americans ages 45-54. If you were able to make catch-up contributions, you would exceed the median. And this doesn't even include an employer match.
Your balance grows so quickly here because of compounding.
If you invest $24,500 this year and leave it alone for a decade, your investment will (hopefully) earn returns this year that can be reinvested, so in year two, you get to earn returns on a bigger starting balance. This continues over 10 years, so your money is making money for you, and your balance (ideally) grows more quickly each year. Of course, you may not necessarily earn 10% on your money every year. But if you get that average 10% annual return over the decade, your account balance should be pretty close to these amounts. Contribute as much to your 401(k) balance as you can
401(k) plan checklist among forms and other documents.
Of course, maxing out your 401(k) balance may not be possible, given that not everyone has $24,500 (or more) to invest this year. But keep in mind that the table above is just one year of maxed-out contributions, and it assumes you put nothing else into your account. If you invest a smaller amount over time but you invest consistently, you can still make compounding work for you and end up with a much bigger nest egg than the typical American retires with.
The key is to invest as much as you can, starting as early as you can, so you have time for the power of compounding to work for you. A financial advisor can help you to create a personalized investing plan that takes your budget and goals into account, so reach out to one if you need help getting started with investing in your 401(k) or optimizing the contributions you make.
It`s Time To Rethink Passive Investing
For more than a decade, the investing advice aimed at everyday Americans followed a familiar script: automate everything, keep costs low, and don`t touch a thing. And increasingly, investors are realizing that being completely hands-off also means being completely disengaged.
That realization hits like a lightning bolt when you realize not just how much better your returns could be, but that there are amazing offers like one app where new self-directed investing accounts funded with as little as $50 can receive stock worth up to $1,000.
Take back your investing and start earning real returns, your way.